Share Predictions



Quick Summary
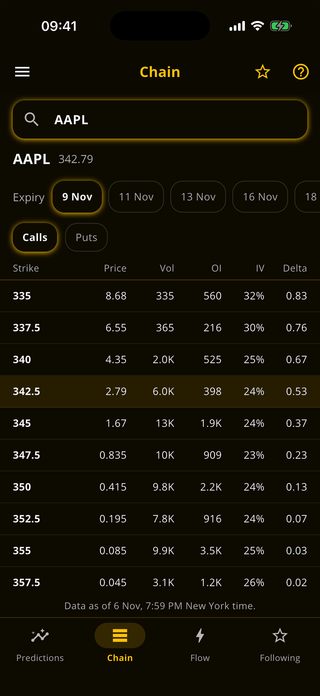
Delta (Δ) measures how much an option's price changes for every $1 move in the stock. Call Delta ranges from 0 to 1.0; Put Delta ranges from 0 to -1.0. Delta also serves as a rough estimate of the probability that the option will expire in-the-money.
In previous posts, we discussed the broad concepts of volatility and premiums. Now, we enter the world of "The Greeks": a set of mathematical risk measurements that estimate how your option price will change.
The most famous, and perhaps the most important Greek of them all, is Delta (Δ).
If you've ever asked, "If the stock goes up by $1, how much money will I make?" then Delta is the number that gives you the answer.
The Definition: What is Delta?
Delta measures how much an option's price is expected to change for every $1.00 change in the underlying stock price.
Think of it as the "speedometer" of your option contract: it tells you how fast your option value moves relative to the stock.
| Calls | 0 to +1.0 |
|---|---|
| Puts | -1.0 to 0 |
Put options have negative Delta because they gain value when stocks fall.
The Delta Formula
New Option Price = Current Price + (Stock Move × Delta)
A Real-World Example
Imagine you own a Call Option for Apple (AAPL).
Scenario 1: Stock rises $1
| Current Option Price | $5.00 |
|---|---|
| Delta | 0.60 |
| Stock Move | +$1.00 |
| New Option Price | $5.60 |
Scenario 2: Stock rises $2
| Current Option Price | $5.00 |
|---|---|
| Delta | 0.60 |
| Stock Move | +$2.00 |
| New Option Price | $6.20 |
Note: This is a simplified example. In reality, Delta itself changes as the stock moves (measured by Gamma).
Delta as Probability (The Secret Shortcut)
While Delta strictly measures price sensitivity, traders often use it as a powerful shortcut to estimate probability.
A Delta of 0.30 roughly translates to a ~30% chance that the option will expire "In-The-Money" (ITM).
| Delta 0.80 | Deep ITM: Very high probability (~80%). Option behaves almost like the stock. |
|---|---|
| Delta 0.50 | At-The-Money: A coin flip (~50%). Market is uncertain. |
| Delta 0.10 | Far OTM: A long shot (~10%). Needs a massive move to profit. |
How Delta Changes ("Moneyness")
Delta is not a static number. It changes depending on where the stock price is relative to your strike price.
In-The-Money
Δ > 0.50
These options are expensive and highly sensitive.
A Deep ITM call with Δ = 0.90 acts almost exactly like owning the stock. If the stock goes up $1, your option goes up $0.90.
At-The-Money
Δ ≈ 0.50
The most active "battleground" for traders.
The market is unsure if these will finish ITM or OTM. Maximum uncertainty = maximum time value.
Out-Of-The-Money
Δ < 0.50
"Lottery tickets" with low probability.
A Δ = 0.10 call means if the stock rises $1, your option only increases by $0.10. You need a massive move.
Delta for Buyers vs. Sellers
Option Buyer. Often wants High Delta (positive for calls, negative for puts). They want the option value to surge when the stock moves in their favor.
Option Seller. Often targets Low Delta. A 0.30 Delta means ~70% chance the option expires worthless: seller keeps the premium.
Frequently Asked Questions
What is Delta in options trading?
Delta measures how much an option's price is expected to change for every $1.00 change in the underlying stock price. For call options, Delta ranges from 0 to 1.0. For put options, Delta ranges from 0 to -1.0. A Delta of 0.60 means the option price should move $0.60 for every $1 the stock moves.
How do you use Delta to estimate probability?
Traders use Delta as a rough estimate of the probability that an option will expire in-the-money (ITM). A Delta of 0.30 suggests approximately a 30% chance of expiring ITM. At-the-money options have a Delta near 0.50, indicating roughly a 50/50 chance.
What is a good Delta for buying options?
It depends on your strategy. High Delta options (0.70-0.90) are safer and move almost like the stock: good for stock replacement strategies. Low Delta options (0.10-0.30) are cheaper but riskier: they require large stock moves to profit. Mid-range Delta (0.40-0.60) offers balance between cost and probability.
Why do put options have negative Delta?
Put options have negative Delta because they gain value when the underlying stock price falls. A put with Delta of -0.40 means the option price increases by $0.40 for every $1 the stock drops. The negative sign indicates the inverse relationship between stock price and put option value.
Does Delta stay constant?
No, Delta changes as the stock price moves relative to the strike price. As an option moves deeper in-the-money, Delta approaches 1.0 (or -1.0 for puts). As it moves out-of-the-money, Delta approaches 0. This rate of change in Delta is measured by another Greek called Gamma.
Summary
Delta is your primary tool for choosing the right "aggression level" for your trade.
Want a safer, stock-replacement strategy? Buy High Delta (0.70+).
Want a speculative, high-reward opportunity? Buy Low Delta (0.10-0.30).
Want to estimate your odds? Look at the Delta as probability.
However, Delta itself isn't constant. As the stock price moves, Delta changes speed. That acceleration is measured by the next Greek: Gamma.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Options trading involves significant risk of loss and is not suitable for all investors. You could lose your entire investment. Past performance does not guarantee future results. Always do your own research and consider consulting a qualified financial advisor before making investment decisions.