Share Predictions



Quick Summary
The Option Premium is the market price of an options contract. It consists of two parts: Intrinsic Value (the real, tangible value) and Extrinsic Value (the time and volatility component). Premiums are quoted per share, but contracts cover 100 shares, so a $2.00 premium actually costs $200.
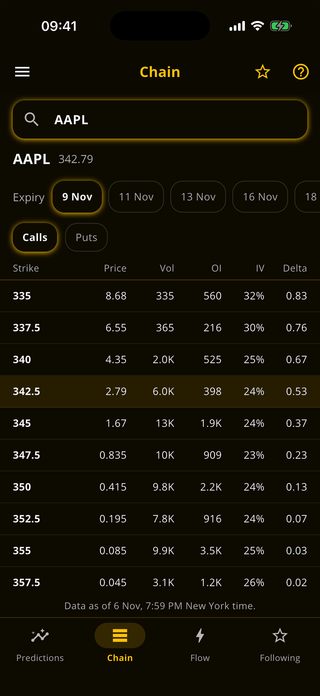
If you've ever looked at an options chain, you've probably noticed something puzzling: prices change constantly. A Call Option might be priced at $2.50 in the morning, and by the afternoon, it's trading at $3.00, even if the stock price itself barely moved.
This price is called the Option Premium.
Understanding what the premium represents, and what factors drive it up or down, is fundamental to trading options effectively. Without this knowledge, you're essentially buying something without understanding what determines its price.
The Definition: What is an Option Premium?
The Option Premium is simply the current market price of an options contract. It is the cost paid by the buyer and the income received by the seller (also called the "writer").
The 100-Share Multiplier. Option premiums are quoted per share, but standard contracts cover 100 shares. If you see a premium listed as $1.50, the actual cost to buy that contract is $150 ($1.50 × 100).
Example. You see a Tesla Call Option with a premium of $5.25. To buy one contract, you pay $5.25 × 100 = $525. If you sold that same option, you would receive $525 (minus any commissions).
The Two Building Blocks of Premium
The price of an option isn't random. It's calculated by combining two distinct components:
Premium = Intrinsic Value + Extrinsic Value
Intrinsic Value (The "Real" Value)
This is the tangible, immediate value of the option if you were to exercise it right now.
- Only In-The-Money (ITM) options have intrinsic value
- Calculation: difference between stock price and strike price
- Can never be negative (minimum is zero)
Extrinsic Value (The "Time & Hope" Value)
This is the speculative portion representing the possibility that the option could gain more value before expiration.
- Out-Of-The-Money (OTM) options are 100% extrinsic value
- Primarily determined by time and volatility
- Erodes as expiration approaches
Intrinsic Value Example. Stock Price: $55 | Call Strike Price: $50
Intrinsic Value = $55 - $50 = $5. If this call's premium is $7, then the remaining $2 is extrinsic value.
The Three Main Factors That Drive Premium
Why does the premium fluctuate? While complex mathematical models (like Black-Scholes) calculate precise prices, they fundamentally rely on three key variables:
Price of the Underlying Stock
This is the most straightforward factor. The option's value is directly tied to the stock's movement.
Calls: When the stock goes up, the premium generally increases
Puts: When the stock goes down, the premium generally increases
Time Until Expiration (Theta)
Time has value in options trading. An option with more time remaining is worth more because there's more opportunity for the stock to make a favorable move.
Time Decay: As expiration approaches, the extrinsic value portion of the premium erodes. This process accelerates dramatically in the final weeks.
An option with 30 days left might have $3 of extrinsic value. The same option with only 3 days left might have just $0.50 of extrinsic value, even if the stock hasn't moved at all.
Implied Volatility (The "Fear" Factor)
This is the most overlooked factor by beginners. Implied Volatility (IV) measures how much the market expects the stock price to swing in the future.
High IV: When a stock is expected to swing wildly (e.g., before earnings), premiums become expensive. Sellers demand more compensation for the higher risk.
Low IV: When a stock is stable and "boring," premiums become cheap. There's less expected movement to price in.
The "Volatility Crush" Trap
One of the most common mistakes beginners make involves buying options before major events like earnings announcements.
The Scenario. You buy a call option right before a company announces earnings, expecting the stock to jump. The earnings are good, the stock rises 5%, but your option loses money. What happened?
Before earnings, implied volatility is elevated because no one knows what will happen. This uncertainty is priced into the premium as extra extrinsic value.
After the announcement, uncertainty drops immediately. The "unknown" becomes "known." This causes implied volatility to collapse, often called a volatility crush or "IV crush."
The extrinsic value portion of your premium can evaporate overnight. Even if the stock moved in your direction, the volatility collapse might outweigh the gains from the stock movement.
Bid vs. Ask: The Hidden Cost
When looking at option premiums, you'll see two prices listed:
| Bid | $2.45 |
|---|---|
| Ask | $2.55 |
- Bid: The highest price a buyer is currently willing to pay. This is the price you receive when selling.
- Ask: The lowest price a seller is willing to accept. This is the price you pay when buying.
The difference between these two is called the spread. This spread is essentially a transaction cost.
Tight Spread (Good). Liquid stock (e.g., Apple, SPY):
Bid: $1.48 / Ask: $1.50 (spread: $0.02)
Minimal cost to enter/exit
Wide Spread (Dangerous). Illiquid stock:
Bid: $1.00 / Ask: $1.50 (spread: $0.50)
Lose $50 per contract instantly
Wide Spreads Kill Returns. With a wide spread, you lose value the moment you enter the trade. If the bid-ask is $1.00 / $1.50, you buy at $1.50 but can only sell immediately at $1.00: a 33% loss before the stock even moves. Stick to liquid options with tight spreads.
Frequently Asked Questions
What is the option premium?
The option premium is the current market price of an options contract. It's the cost paid by the buyer and the income received by the seller. Premiums are quoted per share, but since standard contracts cover 100 shares, a $2.00 premium means you actually pay $200 to buy one contract.
What is intrinsic value vs extrinsic value?
Intrinsic value is the tangible, real value of an option if exercised immediately: only ITM options have it. Extrinsic value (also called time value) is the speculative portion representing the possibility the option could gain more value before expiration. Premium = Intrinsic Value + Extrinsic Value.
Why do option premiums change constantly?
Option premiums fluctuate based on three main factors: the underlying stock price, time until expiration (time decay), and implied volatility. Even if the stock doesn't move, the premium can change significantly due to volatility shifts or time decay eroding the extrinsic value.
What is time decay (theta) in options?
Time decay is the erosion of an option's extrinsic value as expiration approaches. An option with 30 days left is worth more than the same option with 3 days left because there's more time for a favorable move. This decay accelerates in the final weeks before expiration.
What is the bid-ask spread and why does it matter?
The bid is the highest price buyers will pay; the ask is the lowest price sellers will accept. The difference is the spread. Wide spreads (common in illiquid options) mean you lose value immediately upon entering a trade. Tight spreads on liquid stocks like Apple mean lower transaction costs.
Summary
The Option Premium is not a static price tag: it's a dynamic number that reflects the market's assessment of value, time, and uncertainty.
When you buy an option, you're buying a decaying asset. Every day you hold it, the time value portion of your premium erodes. For the premium to increase, the stock price or volatility must move favorably enough to outpace that daily decay.
Understanding this dynamic is what separates informed options traders from those who are simply gambling on direction.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Options trading involves significant risk of loss and is not suitable for all investors. You could lose your entire investment. Past performance does not guarantee future results. Always do your own research and consider consulting a qualified financial advisor before making investment decisions.